From the man who tabbed NVIDIA before it soared 6,271%
over 7 years at its peak
Wall Street’s Hottest Stock Has a Waiting List. Here’s How to Skip It.
Wealthy investors are lining up for Anthropic shares and coming up empty. Tech Visionary, Matt McCall, says you can get into a backdoor opportunity today for less than $100 a share.
Anthropic, the company behind Claude, is set to go public at a record $2 trillion valuation.
It could top SpaceX as the biggest IPO in history.
And right now, almost nobody can buy a single share.
One Wall Street broker, whose firm trades about 1,000 private stocks, told TechCrunch:
“The hardest stock to source in our marketplace is Anthropic. There’s just no sellers.”
Even Goldman Sachs is charging clients 15% to 20% of their profits just for a way in.
The Line Is Out the Door
Meanwhile, people who already own a piece of Anthropic are holding on tight.
While everyone else is stuck in line. Even wealthy investors are struggling to get shares.
And it’s all leading to the most anticipated IPO in history.
When Anthropic finally goes public, millions of regular folks will rush to buy whatever they can get.
But tech legend Matt McCall isn’t getting in line.
“Most people are going to wait for Anthropic to go public and then buy as many shares as possible,” he says. “But I think that’s a huge mistake.”
Who Is Matt McCall?
There is a short list of analysts in America who were early on the AI boom.
Matt McCall is one of them.
He’s the Head Innovation Strategist at Monument Traders Alliance and editor of The McCall Innovation Report.
Over the past two decades, McCall has written about 50 stocks that went on to peak gains of 1,000% or more. Including:
- Tesla, before it climbed as high as 3,129%
- NVIDIA, before it soared a peak 6,271% in 7 years
- AMD, which he singled out in 2009
That’s why people call him “Mr. 1,000%.”
On March 6, 2009, McCall went on FOX Business and gave away nine stocks. One was AMD, trading around two dollars. By 2026 it rose 25,000%, enough to turn a $5,000 stake into more than $1.28 million.
No Waiting List Required
McCall’s play isn’t Anthropic. It’s a stock linked to Anthropic that you can buy right now in a regular brokerage account.
No waiting list. No special broker. No fighting Wall Street for scraps.
He calls it a “Second IPO.”
It may sound too good to be true. But it has happened before.
When Rivian went public in 2021, Ford owned a 12% stake. In the six months around Rivian’s IPO, Ford shares roughly doubled.
Yahoo quietly built a huge stake in Alibaba. In the two years around Alibaba’s IPO, Yahoo shares could have tripled your money.
It happened again shortly after EchoStar acquired $8.5 billion in SpaceX shares. In the months leading up to the SpaceX IPO, its shares soared 600%.
Now it’s happening again!
Anthropic’s “Silent Partner”
Years before the IPO frenzy, a much smaller firm took a $100 million stake in Anthropic. It beat Apple, NVIDIA, Amazon and Google to the punch.
Today, the entire company is valued at less than $15 billion. That’s 100x smaller than Anthropic.
McCall believes its early stake could cause it to double or triple in the years ahead.
And you can buy it for less than $100 a share.
We sat McCall down in front of our cameras to get the whole story. He even gave away the name and ticker.
For the time being, you can watch it free.
|
“If history repeats… investors could double or triple their money in the years ahead.” – Matt McCall
CoreWeave’s Debt Load Is What Tuesday’s Move Is Actually About
Markets don’t need a revenue miss to punish CoreWeave on Tuesday evening. They only need the balance sheet to stay as frightening as it already is.
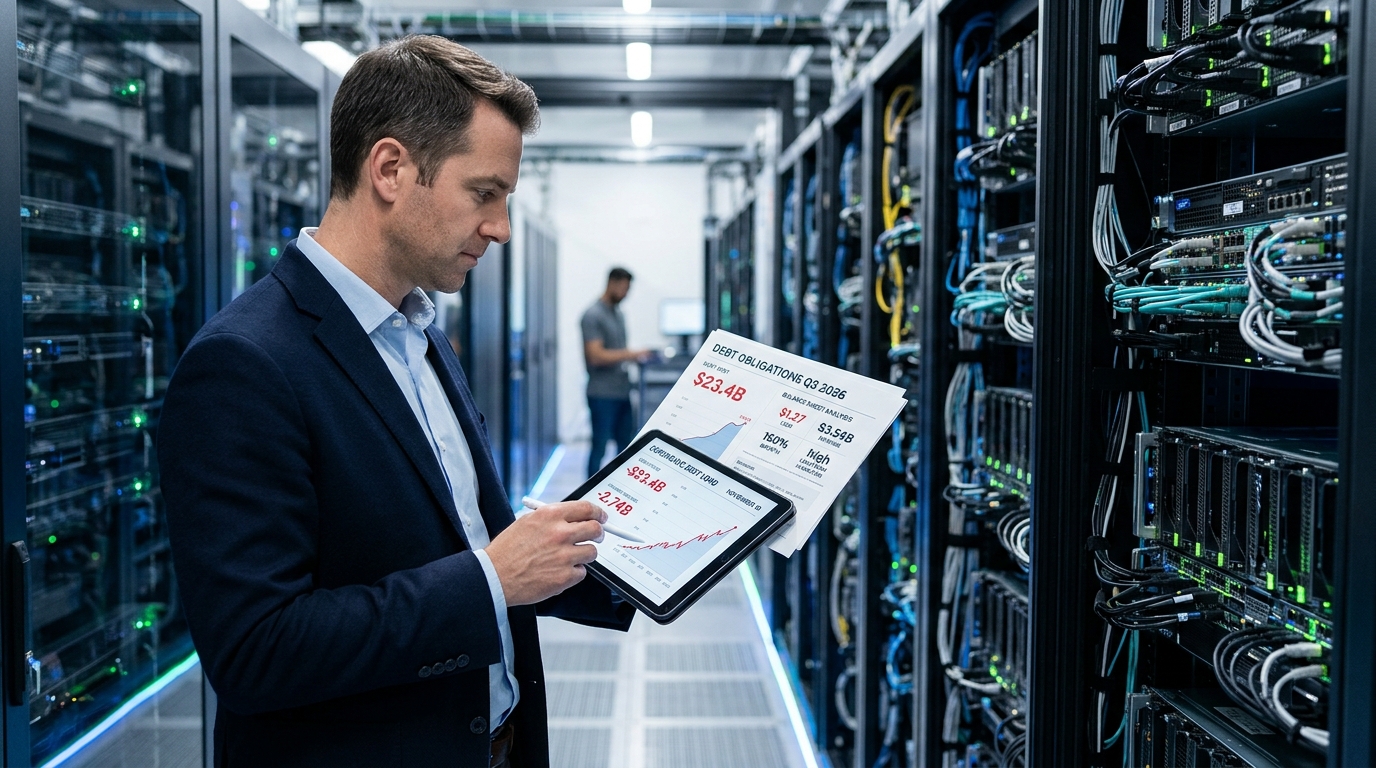
CoreWeave reports Q3 2026 results on November 10, with Wall Street expecting a loss of $1.27 per share on revenue of $3.54 billion. That compares to Q3 2025 revenue of $1.36 billion, implying year-over-year growth north of 160%. The growth rate is not the problem. The debt is.
CoreWeave reported total indebtedness of $35.6 billion as of June 30, 2026, plus operating lease liabilities of about $16.3 billion, for roughly $52 billion of debt and lease obligations combined. In the second quarter, interest expense, net was $640 million against $2.575 billion in revenue. So while revenue compounds at triple digits, cash bleeds to creditors at a rate that makes profitability a distant destination.
What the Selloff Already Knows
The stock lost 38.5% from October 5 to November 3 alone. Over the past 52 weeks, CRWV traded between a high of $138.25 and a low of $40.58. This is not a correction. It is a revaluation of credit risk into equity, and the equity market is following the bond market’s lead. Elon Musk stated publicly that debt markets have “almost entirely shut off” for companies without substantial revenue independent of AI data centers, and spreads on CoreWeave’s credit default swaps have moved into levels commonly associated with financial distress.
CoreWeave’s Q2 revenue backlog was approximately $104 billion, but interest expense, net was $640 million against adjusted operating income of $128 million. As one analyst framed it, the AI bubble lives in the debt more than the demand, and a $104 billion backlog does not cover interest until the data centers are built and customers pay. That structural gap is what Tuesday’s call must address.
The financing pressure is not unique to CoreWeave. Six major hyperscalers are projected to run negative free operating cash flow as AI infrastructure spending outpaces revenue conversion.
Nebius follows two days later, reporting Q3 2026 results before market open on November 12, with analysts expecting a loss of $0.71 per share on revenue of $905.75 million. Nebius has described a materially different balance sheet than CoreWeave’s in recent company materials, and its leverage profile should be evaluated on its own filings and updates rather than assumed to match the neocloud complex.
Options Market Analysis
Options imply roughly a 22% move for CRWV when the company releases earnings November 10 after the market close. That number deserves skepticism. The company’s actual stock price movement exceeded the options-implied move in four of the past six earnings announcements, including a roughly 19% move on August 11 versus an implied move around the mid-teens. The options market has consistently underpriced CoreWeave’s post-earnings range.
Put/call positioning and implied volatility have both remained elevated into the event, consistent with a market that is paying up for convexity and protection. With IV this elevated, premium sellers carry real risk of being overrun by the actual move.
Structured Trade Framework
Bull case: For traders expecting CoreWeave to beat consensus and guide Q4 revenue above the $3.45 billion to $3.6 billion range it projected last quarter, a defined-risk structure such as a bull call spread in the $50 to $65 strike range for the November 14 expiry limits downside to premium paid while capturing a rebound toward the analyst consensus target of $129 to $134.
Bear case: If you believe the debt refinancing risk is not yet fully priced and management guidance disappoints on the Q4 outlook or cost of capital, a put spread below current spot, structured around the $40 to $45 range, defines the risk while expressing a view that the stock revisits its 52-week low. CoreWeave has beaten consensus EPS estimates in only two of the last four quarters, leaving room for downside surprise.
Neutral case: With IV in the top range of recent history, a short strangle or iron condor centered on the current $45 to $47 price range monetizes elevated premium if the stock settles within a 15% band post-earnings. The historical record of moves exceeding implied ranges means wings should be wide.
Risk Analysis and Forward Outlook
The consensus EPS estimate for the quarter has been revised 14.61% higher over the last 30 days, suggesting analysts expect a beat on the loss line. Revenue growth is not in question. The question is whether management can demonstrate a credible path on debt costs before the credit market’s concern becomes a self-fulfilling constraint on growth. Analysts hold a Moderate Buy consensus based on 22 buys and five holds, with an average price target of $129.68, implying the fundamental case remains intact if the credit story stabilizes.
Action Checklist
- Watch guidance on Q4 revenue range versus the $3.45 billion to $3.6 billion prior guide.
- Monitor management commentary on debt refinancing timelines and cost of capital.
- Compare actual post-earnings move against the implied range before entering any position.
- For defined-risk structures, size to no more than 2% of portfolio given CRWV’s history of exceeding implied moves in both directions.
- Track Nebius November 12 results as a secondary read on sector-wide credit appetite and demand.