September 26, 2026
Bonus Content: Accenture’s Bookings Are the Real Audit of Enterprise AI Spend
Dear Reader,
The Trump administration has been pumping massive cash into small resource companies lately…
Companies vital to national security.
As you can imagine, these “government targeted” stocks have soared in value.
Just look at the results:
Trilogy Metals – up 388% in 8 days.
MP Materials – up 216% in 4 months.
Lithium Americas – tripled in 3 weeks.
And America’s Economist, Dr. Mark Skousen, says it’s about to happen again.
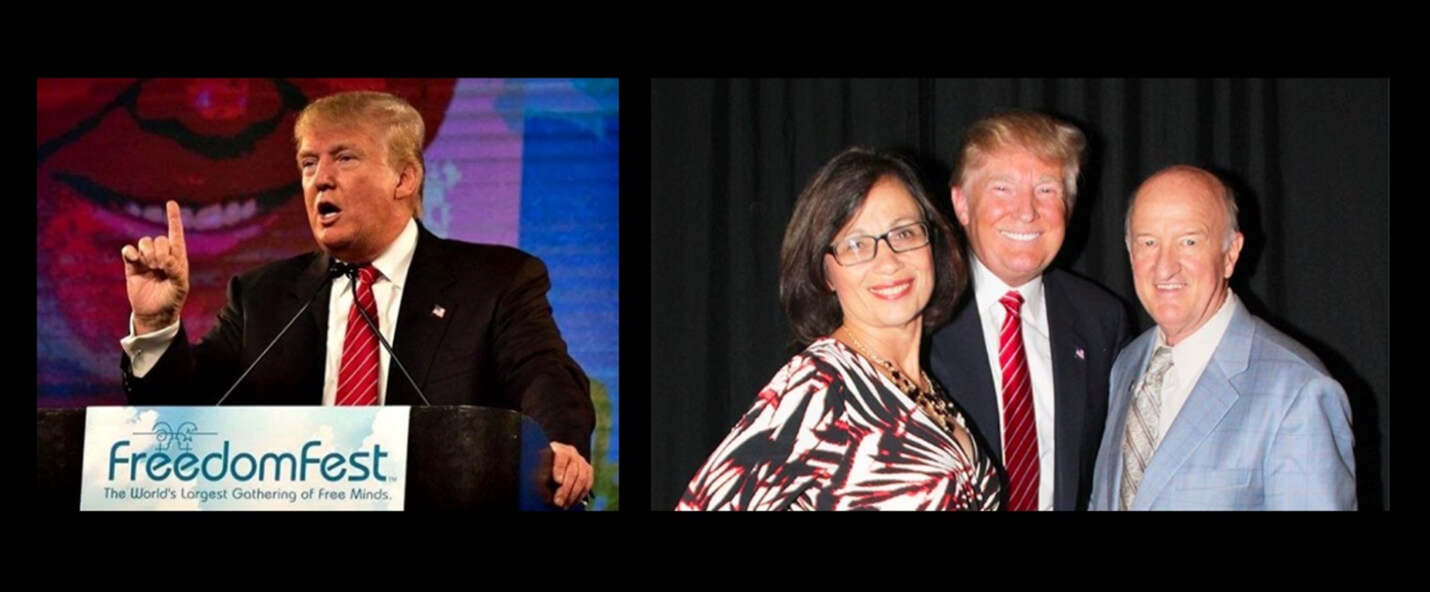
Keep in mind… Skousen knows the President personally after Trump spoke at his FreedomFest conference.
And he’s also developed close relationships with Senators Rand Paul, Mike Lee, and others.
He’s learned what’s important to them.
And one thing they’ve made clear.
The current administration will take stakes in companies they deem important to national security.
Now, Dr. Skousen says he believes it will happen again.
This time with a much smaller company.
And in anticipation, he’s purchased 10,000 shares of his own.
Here’s why…
This company is the only domestic producer capable of delivering one strategic mineral America can’t do without.
That’s why Tesla just signed a binding agreement to purchase 75,000 metric tons from this company.
And it’s why the government has already handed the company grants totaling $130 million.
Dr. Skousen believes the U.S. government could take a stake at any moment in the days ahead..
He breaks down the full situation right here – read it before this stock makes headlines.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
P.S. The last time Mark felt this way about a resource stock, he turned $50,000 into a rare $1.3 million over just three years. Don’t sit on this one.
Accenture’s Bookings Are the Real Audit of Enterprise AI Spend
Markets do not need another EPS beat. They need to know whether enterprises are genuinely buying AI implementation or simply budgeting for it. Accenture’s fiscal Q4 report, due before the open on October 1, is the clearest answer the market gets to that question. The company sits at the exact interface between hyperscaler ambition and corporate execution, the firm clients call when they want to turn a vendor’s AI product into an operating system for a business.
The stakes are larger than one quarter’s results. Goldman Sachs has put a headline number on the next leg of hyperscaler AI infrastructure spending, projecting it could rise by more than half next year to $1.2 trillion. Goldman has also argued that the revenue required to earn an attractive return on that level of investment is still a heavy lift. That gap, infrastructure spending at scale, revenue conversion still lagging, is precisely Accenture’s opportunity and its problem. Bookings tell you which side is winning.
The tension between AI infrastructure commitments and actual returns is not unique to Accenture’s clients. S&P Global’s own projections point to negative free operating cash flow across much of the sector as capex accelerates — a dynamic explored in detail in how six major tech companies are funding AI spending and which can sustain it. The answer to that question shapes how aggressively enterprises will commit to the large transformation programs Accenture depends on.
The Data Behind Thursday’s Report
Accenture will host a conference call at 8:00 a.m. EDT on Thursday, October 1, 2026, to discuss its fourth-quarter and full-year fiscal 2026 financial results. Analysts expect the company to report quarterly earnings of $3.18 per share, up from $3.03 per share in the year-ago period, on consensus quarterly revenue of $18.04 billion.
The trajectory into this quarter has been choppy. Q3 revenue reached $18.72 billion, up 6% in U.S. dollars and 3% in local currency, but new bookings came in at $19.32 billion, a decrease of 2% in U.S. dollars and 3% in local currency. That bookings slip followed a record Q2, where new bookings hit $22.11 billion, up 6% in U.S. dollars but only 1% in local currency, with diluted EPS of $2.93. The local currency stagnation in bookings is the number worth watching Thursday, it strips away FX tailwinds and reflects the underlying demand signal.
Management has been explicit that AI-related demand is building, pointing to continued momentum in advanced AI work and larger transformation programs. But the options market is focused on a narrower question: does the Q4 bookings number sustain that trajectory, and does management offer a fiscal 2027 revenue guide that justifies current valuation?
What the Market Expected, and Why the Reaction Could Surprise
Q3’s stock reaction illustrated the risk asymmetry around this name. Accenture tumbled in early trading after unveiling disappointing Q4 sales guidance alongside its Q3 results, with shares down more than 16% at one point. For the current quarter, management guided sales ranging from $17.75 billion to $18.4 billion, below the then-consensus view clustered around $18.5 billion. A miss on the high end of guidance produced the sharpest single-session drawdown investors have seen in years. That context matters heading into Thursday.
That kind of violent guidance-driven reaction stands in contrast to how other enterprise technology names have traded around negative analyst events this year. Oracle’s experience offers a useful counterpoint — a case where a formal downgrade failed to push the stock lower, suggesting that in AI-adjacent names, the market is increasingly willing to look past near-term signals toward backlog and demand visibility, a pattern examined in why Oracle’s stock rose even after analysts cut their rating. Whether Accenture earns the same benefit of the doubt depends almost entirely on what Thursday’s bookings number says about forward demand.
The stock has also lagged the broader market over the past year. Over the last 52 weeks, ACN is down roughly 46% while the S&P 500 is up in the mid-teens. Investors worry AI will erode demand for Accenture’s hours-based consulting, and a stronger dollar has added pressure by squeezing IT budgets.
On the government side, the company is adding hard-contract revenue. Accenture Federal Services will build out the core software connecting hundreds of military data streams to the Pentagon’s War Data Platform, under a contract worth up to $821 million over five years. A separate five-and-a-half year, $480.4 million Army contract was awarded recently to help develop an AI-centric system for managing tasks and correspondence across the entire Defense Department. These awards arrive in fiscal Q4’s window and belong in the bookings count.
Options Market Analysis
The options market is pricing an expected move of 7.79%, or roughly $14.38, with IV Rank at 81.48 and implied volatility at 52.1% against realized volatility of 42.6%. With IV at 45.1% versus realized at 42.81%, options are pricing more movement than the stock has recently delivered. That premium matters for structure selection.
The stock traded between $118.15 and $291.09 over the past 52 weeks, and is down roughly 46% over that span. The chain is not mispriced wildly, but it leans rich into an event where the guide, not the quarter, is the actual variable.
Structured Trade Framework
Bull case: For traders expecting bookings to recover toward the $21 to $22 billion range and a fiscal 2027 revenue guide of 5% or better in local currency, a defined-risk long structure, a call spread expiring October 17, with the long strike near the money and the short strike just above the implied move, captures a positive reaction without unlimited downside if guidance disappoints again.
Bear case: If you believe the bookings trend established in Q3 continues and management guides fiscal 2027 conservatively, a put spread positioned just below the current price and extending to the lower bound of the Q3 post-earnings range captures the downside within a defined cost. Given elevated IV rank, buying premium outright is expensive; spreads limit the cost of that richness.
Neutral case: With IV elevated into the event, a short iron condor, selling strikes just outside the implied 7.79% move on both sides, buying wings further out, profits from a post-earnings volatility collapse if the stock resolves inside the priced range. This is a volatility-selling framework, not a directional one, and requires discipline on sizing.
Risk Analysis and Forward Outlook
Full-year FY26 revenue growth is expected at 3% to 4% in local currency, with Q4 revenue outlook spanning 1% to 5% in local currency. That four-point range is unusually wide and reflects genuine uncertainty. Management guided Q4 revenue growth of 1% to 5% in local currency, noting that the low end was in play if late-quarter deterioration continued; the distance between those outcomes comes down to what investors will pay for each dollar of earnings.
The fiscal 2027 guide is the event within the event. A sub-5% local currency growth outlook would confirm the market’s fear that enterprise AI budgets are rotating toward direct hyperscaler contracts and away from third-party implementation at scale. A guide above 6% reframes the bookings deceleration as cyclical, not structural. That distinction is worth a double-digit percentage move in either direction.
Action Checklist
- Key number: Q4 new bookings versus the $19.32 billion Q3 level; any recovery toward $21 billion changes the sentiment entirely.
- Guide watch: FY27 local currency revenue growth, below 4% is bearish, above 6% is the bull trigger.
- IV context: IV Rank at 81.48 favors spread structures over outright long premium ahead of the event.
- Expected move: Options price ±7.79% ($14.38); structures positioned outside this range carry lower probability but higher reward-to-risk.
- Post-earnings: Watch IV crush on October 2; premium sellers should plan to close or roll within 24 to 48 hours of the release.
- Sector read: IBM, INFY, and CTSH all carry correlation to Accenture’s bookings signal; a weak guide from ACN typically pressures the peer group within the same session.
IBM’s exposure to that correlation is worth understanding on its own terms before Thursday’s open. The company has been navigating a dual catalyst in enterprise AI — one tied to software and consulting demand, the other to hardware infrastructure — and the interplay between those two drivers shapes how sensitive IBM is to any signal Accenture sends about enterprise implementation budgets. IBM’s double catalyst in the AI hardware and enterprise cycle lays out why the company’s positioning makes it one of the more reactive names if Accenture’s guide disappoints.