September 26, 2026
Bonus Content: Jabil’s $9.6 Billion Quarter Lands Before Micron
Why Did Trump Just Ban America’s Most Powerful AI?
It’s not Nvidia. It’s not OpenAI. It’s not Google.
It’s a San Francisco AI lab whose technology is used by eight of the ten largest companies in America – and which Bloomberg calls the highest-revenue AI company on earth.
Trump banned it from every federal agency and the Pentagon blacklisted it. The reason isn’t what you think. Full details here.
AI COULD KILL US ALL!
That’s not my prediction.
It’s what people building AI are now warning.
A former Anthropic researcher just quit, saying AI labs are “gambling with our lives.”
Then Anthropic’s own alignment lead went further…
He says there’s a greater than 10% chance advanced AI could kill all humans within the next decade.
Terrifying?
Absolutely.
But here’s what caught my attention as an investor…
Washington is already treating Anthropic’s technology as a national-security issue.
And if these warnings accelerate Washington’s intervention will become inevitable.
Investors positioned before this happens stand to benefit most.
Addison Wiggin has put his extensive presentation right here…
This ad is sent on behalf of Banyan Hill Publishing.
If you would like to unsubscribe from receiving offers for Market Rebellion, please click here.
Jabil’s $9.6 Billion Quarter Lands Before Micron
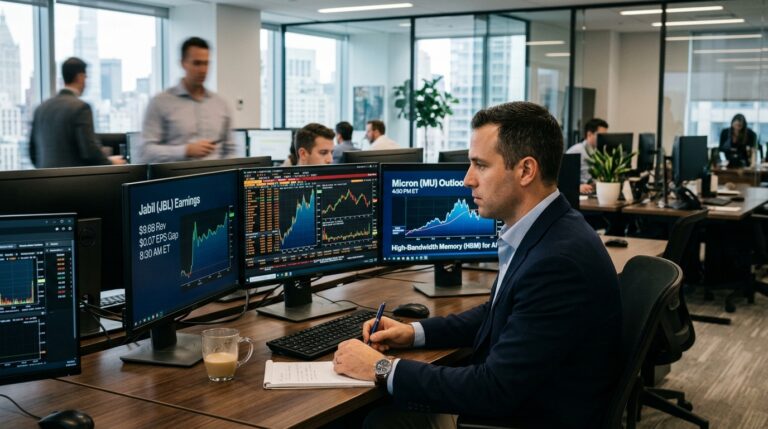
Wednesday, September 30 is not a single event. It is two events, stacked hours apart, both tied to the same AI infrastructure cycle, and both capable of moving the other. Jabil (JBL) reports fiscal Q4 before the open at 8:30 a.m. ET. Micron (MU) follows after the close with its earnings call scheduled for 4:30 p.m. ET. For traders with positions in either name, the sequencing matters as much as the numbers.
This is not about which company is more important. It is about which one sets the tone. Jabil goes first, and the gap between its own guidance and Wall Street’s consensus is precisely where the morning’s direction gets decided.
The Numbers on the Table
Jabil guided Q4 to a revenue range of $9.2 billion to $10.0 billion, with core diluted EPS of $3.80 to $4.20, putting the midpoints at roughly $9.6 billion in revenue and $4.00 in adjusted EPS. Consensus has settled above that: analysts are expecting $4.07 per share on $9.7 billion in revenue. The gap is $0.07 on EPS and $100 million on revenue. Those are not wide margins for a company with a roughly $32 billion market cap trading near $300.
For context, Q4 of fiscal 2025 produced $8.3 billion in revenue and $3.29 in core EPS. The consensus implies roughly 17% revenue growth and about a 24% jump in per-share earnings year over year. That is what a beat would confirm. A miss of that same $0.07 against a guidance midpoint already below consensus would raise questions the market has been willing to look past during the AI demand surge.
What the Quarter Is Actually About
Jabil’s Intelligent Infrastructure segment generated $4.2 billion in Q3, up 21% year over year, as cloud, data center, and networking programs expanded. Full-year AI-related revenue is now tracking toward $13.6 billion, up from roughly $9 billion in fiscal 2025, a 50% advance driven by demand for custom-engineered rack assemblies and liquid-cooled server chassis. The company has also committed $500 million to U.S. manufacturing capacity for cloud and AI data center customers, targeting Southeast U.S. operations by mid-calendar 2026.
Wednesday’s call will also introduce fiscal 2027 guidance. UBS has suggested AI-related revenue could reach $20 billion in FY27. That forward frame matters more than the Q4 beat-or-miss for long-duration holders.
Goldman Sachs cut its price target from $482 to $375 on September 8, citing near-term uncertainty. Barclays and Stifel both raised targets to $426 and $460, respectively, in June following the Q3 raise. The range of analyst views is wide, which amplifies the directional weight of Wednesday’s quarter.
Options Positioning
Options data compiled by Bloomberg prices an 8.6% implied move for JBL into the September 30 report. With the stock near $300, that equates to roughly a $25.80 band in either direction. Historically, JBL has exceeded its implied move in two of the past eight earnings events: a 17.4% jump in September 2024 against a 6.3% implied move, and an 11.0% rally in June 2025 against a 7.6% implied move. The two most recent reports, however, underdelivered relative to implied volatility: a 3.5% move in June 2026 against an 8.9% implied move, and a 3.0% move in March 2026 against a 10.4% implied move.
IV rank sits at 74, placing current premiums near the top of their 52-week range. The put-to-call ratio on the options chain is running near 0.58, indicating call-side skew. Elevated IV rank at 74 means premium sellers are collecting richer credits than they would outside an earnings window. For buyers, the bar to profit on direction is higher than it looks.
Defined-Risk Frameworks
Bull case. If you believe Jabil comes in above $4.07 EPS on $9.7 billion in revenue and provides FY27 guidance consistent with $20 billion in AI revenue, a defined-risk structure would be a call spread: buying the October 3 $310 call and selling the $335 call. Maximum risk is the net debit paid; maximum gain captures a move to or above the short strike. An outright long call at current IV levels requires roughly a 9% move just to break even, which is the full implied move.
Bear case. For traders expecting a miss on EPS or a cautious FY27 guide, a put spread below the implied move makes sense: buying the October 3 $285 put and selling the $260 put. The spread caps loss at the premium paid and profits if the stock drops below $285, inside the lower end of the 8.6% implied range.
Neutral case. With IV rank at 74 and two consecutive quarters of realized moves well below implied, a short iron condor using the $260 put, $285 put, $335 call, and $360 call collects premium assuming the stock stays inside the implied range. Risk is defined to the difference between strikes minus net credit received. This structure benefits directly from the post-earnings IV compression that has characterized JBL’s last two reports.
Risk Factors
The Micron read-across is real. If Micron’s after-close report delivers a significant positive surprise, the AI infrastructure group opens Thursday with momentum that may already have priced into JBL Wednesday morning. Conversely, a Micron miss on memory margins could shift the supply-chain assumptions embedded in Jabil’s guidance. Memory inflation, specifically higher DRAM and HBM costs Jabil absorbs as a contract manufacturer, is the margin compression risk most analysts have flagged but few have quantified. Component cost pressure that management flags on the call would be new information the consensus has not embedded.
Forward Outlook
The stock’s 52-week range of $189.60 to $428.93 frames how much sentiment has already moved. At $300, JBL is trading about 30% below its June 17, 2026 peak. The Q4 report, combined with Wednesday’s FY27 guidance, determines whether that discount reflects a buying opportunity in a structurally growing AI supply chain, or a proper re-rating of a name that moved too far too fast on AI optimism.
Action Checklist
- Verify the EPS print against $4.07 consensus, not the company’s own $4.00 midpoint
- Monitor the Intelligent Infrastructure segment revenue against the $4.2 billion Q3 baseline
- Listen for FY27 AI-related revenue guidance; $20 billion is the UBS bull case threshold
- Watch for any language on memory cost inflation or component pricing headwinds
- Check Micron’s after-hours reaction for AI infrastructure read-across before sizing any overnight JBL position
- For options traders: IV will compress sharply post-announcement regardless of direction; size defined-risk structures accordingly